FAQ
About the Company
What is the stock code?
The Company's stock code (ticker) is 5027.
When did the company go public?
The Company went public on March 29, 2023.
What is the background of the company?
AnyMind Group was founded in Singapore in April 2016 and currently operates from 22 offices and locations across 15 markets worldwide. AnyMind Group is a technology company that provides a one-stop platform for solutions such as brand development, manufacturing management, media management, e-commerce enablement, marketing and logistics management.
What kind of business do you operate?
Enterprise Growth business:
We develop e-commerce and marketing support platforms for enterprise clients and provide them in combination with operational support. We offer one-stop support covering everything from brand design and planning, production management, e-commerce site construction and operation, marketing, live commerce, and logistics management, to AI implementation and digital transformation. In our financial results, this business domain is disclosed under two segments: Marketing business and D2C/E-Commerce business.
Publisher Growth business:
We provide advertising revenue optimization and user acquisition support utilizing our platform for publishers operating web media and mobile applications.
Creator Growth business:
We provide comprehensive support for video creators and influencers to facilitate their activities, covering content monetization, sponsor acquisition, merchandise development, and management.
Regarding the control of hiring, please explain how you will balance this with business growth.
Disclosed on October 1, 2025
To achieve both business growth and profitability, we are currently taking a balanced approach to our hiring activities, tailoring them to the situation of each business.
Specifically, in our operational delivery and corporate departments, the increase in personnel is being controlled on the premise of improving operational efficiency, including through the use of AI. On the other hand, we are continuing strategic hiring for front-office roles (sales and business development) in our growth businesses, as well as in our product development division, centered on the areas necessary to achieve our business plan. Furthermore, we are also working on the optimal allocation of existing personnel and promoting inter-departmental transfers based on aptitude, thereby striving to maximize the utilization of our internal human resources.
By improving productivity through this optimization of hiring and maximization of internal resources, we aim to achieve revenue growth from the next fiscal year onwards while controlling the increase in our number of employees.
Please tell us about your human resources strategy and the current recruitment situation.
Disclosed on October 1, 2024
Our human resources strategy is characterized by its fusion of a global outlook with local characteristics. While we have dedicated recruitment teams at each location, we also have a team overseeing global HR strategy and crossborder recruitment. This structure allows us to balance recruitment activities that meet each country's specific needs with the execution of a consistent global strategy.
In terms of competitive advantage in talent acquisition, we have a unique presence as a startup originating from Southeast Asia. We have achieved high growth while maintaining stable profitability improvement and financial soundness, along with the credibility of being a listed company. Moreover, there are very few companies with such a multinational organization and culture. We maximize this unique position to strategically and efficiently attract talent in each country who are eager to build careers in the global internet industry.
We are also strengthening knowledge sharing and talent development. For example, we conduct company-wide monthly knowledge sharing sessions and cross-departmental reporting meetings to promote the horizontal expansion of best practices. Furthermore, we aim to broaden employees' global perspectives and deepen cross-cultural understanding through the promotion of cross-border projects. We also provide diverse and advanced learning opportunities, including AI-support training programs, an internal online learning platform, and level-specific training. Going forward, we aim to establish a sustainable growth foundation by developing flexible human resource strategies that respond quickly to rapid market and technological changes.
About Business
Will the strong performance of the talent management domain in FY2026 Q2 continue going forward?
Disclosed on October 1, 2026
In FY2026 Q2, both revenue and gross profit reached record highs, and results exceeded our internal plan. This was mainly due to the outperformance of the creator-focused domain of the D2C/E-Commerce business and the Creator Growth business, driven by the strong performance of the talent management domain. It should be noted that while most of the revenue from the talent management domain is recorded in the Creator Growth business, the segment in which it is recorded varies depending on the nature of the transaction. For example, revenue from advertising projects is recorded in the Marketing business, and merchandise revenue is recorded in the creator-focused domain of the D2C/E-Commerce business.
The talent management domain is inherently susceptible to a certain degree of revenue volatility due to factors such as large-scale events being held or particular merchandise becoming a hit. In fact, in FY2026 Q2, a project by "seju," a production label operated by our subsidiary GROVE, was very well received, resulting in a larger-than-expected revenue contribution to the creator-focused domain of the D2C/E-Commerce business.
On the other hand, the source of revenue in this domain lies in the value of the IP we develop. Therefore, although quarterly revenue fluctuates depending on the timing of events and merchandise sales, we expect medium- to long-term growth through the expansion of activities by our affiliated talent and the creation of new revenue opportunities.
Could you tell us about the status of cross-border projects in the Enterprise Growth business?
Disclosed on October 1, 2026
Demand for cross-border projects in marketing and e-commerce support remains solid. We operate across Asia and have supported numerous brand expansions, such as from Japan to Southeast Asia.
Currently, our inbound/outbound marketing support in Greater China is expanding, and we expect continued growth in this area. This growth is driven both by helping tourism businesses and brands in Japan and Southeast Asia attract visits and purchases from consumers in Greater China, and by helping clients such as Chinese game publishers expand into overseas markets.
Engagements supporting K-Beauty brands expanding into Japan are also increasing. With SUNSMILE joining the Group in January this year, we are now able to support offline distribution to variety stores and other retailers in addition to our existing e-commerce sales support, further strengthening our support framework for K-Beauty.
We believe this know-how can also be applied to Japanese brands. As part of this effort, we have launched a framework to support marketing in the large U.S. market, and although only a few months have passed since its launch, its scale is expanding rapidly. With regard to J-Beauty in particular, both industry players and the government are taking steps to promote the sector. We will strengthen our collaboration with the Japanese beauty industry to turn these developments into business opportunities.
In the Marketing business, could you explain the factors behind the differences in operating profit margins by country and your initiatives for future improvement?
Disclosed on July 1, 2026
There are two major factors behind the variations in operating profit margins.
In countries such as Indonesia and the Philippines, as a structural issue prior to the introduction of AI, the division of team roles was overly fragmented. As a result, a relatively large number of personnel were required, and productivity per employee had not improved. On the other hand, in locations such as Singapore and Hong Kong, although productivity itself is not poor, high base costs, including personnel expenses, are a factor compressing profit margins.
To address these issues, we are currently working to improve profit margins from the dual perspectives of standardizing business processes and consolidating operational bases.
Specifically, we will sequentially introduce the AI automation processes for tasks such as analysis and proposal creation, which were pioneered in Japan, to each country. By optimizing our operations personnel, we will elevate overall productivity. In addition, we are striving to optimize the cost structure itself by providing support from other countries for the operational tasks handled by high-cost bases. When rolling out these measures globally, there were initially variations in the level of understanding and clarity regarding AI among the different bases. However, with the management team, such as the CCO (Chief Commercial Officer) and CPO (Chief Product Officer), directly leading the projects hands-on in each country alongside the AI team, the adoption at the front lines is currently progressing smoothly.
Regarding the Enterprise E-commerce Growth business, will the increase in revenue per brand continue going forward?
Disclosed on July 1, 2026
Regarding the revenue per brand in the Enterprise E-commerce Growth business, although there is a possibility of a temporary decrease on a quarterly basis, we expect the overall upward trend to continue.
As mentioned previously, this business exhibits seasonality, and the revenue per brand also tends to increase from Q1 through Q4. Currently, however, the momentum of our business growth exceeds this seasonality, enabling us to achieve a continuous increase in revenue per brand.
Looking back at the major factors recently, the acquisition and growth of large clients contributed in FY2025 Q2 and Q3. Furthermore, in FY2026 Q1, the consolidation of SUNSMILE, which has a higher average revenue per brand than our existing business, was a factor pushing up the overall average.
Regarding our outlook, our policy is to continue focusing on acquiring large clients. We anticipate that this will increase the overall number of brands and drive growth in revenue per brand through a change in the mix, as the composition ratio of large brands increases. In addition, for the existing brands we support, we expect further expansion in project scale as they progress with multi-country rollouts of the same brand.
It should be noted that immediately after adding new brands, they are in a ramp-up phase, which has the effect of temporarily pushing down the average revenue per brand. However, we anticipate that this can be fully absorbed by the growth of existing brands. As for the future upward trend in revenue per brand, we expect gradual growth in tandem with the expansion of our business scale, rather than the steep increase seen in Q2 and Q3 of the previous year.
What specific impact will the advancement of AI have on your business?
Disclosed on April 3, 2026
We view the advancement of AI as an opportunity for growth and profitability improvement. There are three main reasons for this.
1. "Source of Value" Difficult to Replace with Generative AI and Resilient Demand
The sources of our competitiveness are our "proprietary data" accumulated over many years and our strong "sales capabilities and global network." In our core influencer business in particular, the personal reach and impact of individuals—driven by their distinct personalities and trusted relationships—constitute the fundamental value, which we believe is difficult for AI to replicate. Precisely because AI is evolving, the distinctive value of human involvement and execution capabilities is becoming even more pronounced, and demand for our services remains resilient.
2. Opportunities to Improve Operational Efficiency
In the Enterprise Growth business especially, operational workloads were traditionally heavy, requiring headcount increases in step with business growth, therefore, the recruitment burden and rising costs were challenges. However, areas such as data management present significant opportunities for AI-driven automation and efficiency gains. By applying our operational expertise to AI, we expect to achieve meaningful productivity improvements.
3. Opportunity Creation and Product Evolution Through AI Across Business Domains
Each business division is proactively responding to changes in the operating environment and pursuing new opportunities. We will build sustainable competitive advantages through AI-integrated service evolution, for example, by deploying a hybrid live commerce solution that combines our in-house generative AI live commerce platform, "AnyLive," with human live. In addition, we are adapting to shifts in market demand, such as strengthening mobile app support within the Publisher Growth domain, an area where near-term market growth is anticipated.
What are your impressions of the TikTok Shop launch in Japan? When do you expect it to start contributing to financial results?
Disclosed on April 3, 2026
Given that TikTok Shop in Japan is still in its early stages, we believe its GMV (Gross Merchandise Volume) is tracking at a reasonable scale and pace of growth. It took approximately one to two years from launch to full-scale growth acceleration in both Southeast Asia and the United States, and we expect Japan to follow a similar growth trajectory. While 2025 was a trial phase, we anticipate a growing number of major brands entering the platform in 2026, and we see significant room for market expansion.
The contribution to our financial results is limited at this point, but we expect it to reach a meaningful scale toward the second half of 2026. In Southeast Asia, by contrast, TikTok Shop has already established itself as a major e-commerce sales channel in each market and is contributing meaningfully to our results.
Importantly, what we emphasize even more is not just standalone sales on TikTok Shop, but channeling the demand created on TikTok to other e-commerce platforms and offline sales. We provide integrated support for sales across multiple channels, including e-commerce marketplaces such as Amazon and Rakuten, as well as the offline distribution network operated by SUNSMILE.
In the cross-border domain in particular, our engagements are primarily structured on a GMV-linked revenue model, where we provide comprehensive operational support across sales channels and our revenue scales with transaction volume. This means our revenue growth is driven by sales expansion across multiple channels, rather than being dependent on any single channel.
We are currently building an integrated online-to-offline sales infrastructure, including through our collaboration with SUNSMILE.
Please provide the outlook for the Enterprise Growth Business going forward.
Disclosed on February 13, 2026
We position the social commerce domain as the core of our medium- to long-term growth strategy, with the Enterprise Growth Business being central to it. In 2025, gross profit in this area achieved high growth at 31.5% year-over-year.
Our strength lies in our ability to provide integrated capabilities across Asia, from social media marketing to e-commerce support. In addition, by integrating technology, data, and operations in-house, we believe we are positioned to further solidify competitive advantages even in a market environment where AI adoption is advancing.
Marketing and commerce support, including e-commerce, are strongly connected in terms of customer data accumulation and upselling opportunities, and by combining them, we create synergies that enhance customer value and profitability. Furthermore, our publisher and creator networks function as strategic assets that support the sales expansion of enterprise brands, accelerating the overall growth of the Enterprise Growth Business.
In 2025, with the rapid expansion of enterprise e-commerce support, we prioritized operational structure and personnel development, which resulted in short-term resource constraints in some areas. However, organizational development is now progressing, and from 2026 onwards, we are establishing a foundation to grow both marketing and e-commerce in a balanced manner.
Going forward, we will continue to strengthen our social commerce support structure that integrates marketing and commerce support, aiming to sustain high growth over the medium to long term.
Please explain the status and future outlook for the Creator Growth Business.
Disclosed on February 13, 2026
Regarding the Creator Growth Business in fiscal year 2025, and as a result of changes in the external environment, gross profit was 2.64 billion yen, a decrease of 22.5% year-over-year.
In light of this situation, to strengthen the Enterprise Growth Business over the medium to long term, we conducted a review of our support areas across the entire Creator Growth business and evaluated fields that could contribute more significantly to future profitability and business synergies.
As a result, we found that for some of the creators we had been supporting, synergies with other businesses, particularly the Enterprise Growth Business, were limited from the perspective of each region's owned characteristics and content attributes. Additionally, there were cases where, even if they were generating revenue at present, medium-term revenue growth potential was low. Furthermore, for some creators, we decided to discontinue support based on considerations such as content quality and brand compatibility.
As a result, the number of supported creators decreased from 2,101 in the third quarter of 2025 to 1,237 in the fourth quarter. On the other hand, the human and operational resources freed up by this have been reallocated to areas with high synergy potential with Enterprise Growth Business and high revenue expansion potential, such as providing support for creators with high affinity for brands and products who can contribute directly to commerce revenue generation, and the social commerce area, including live commerce.
With this reorganization of support areas, in fiscal year 2026, the Creator Growth Business alone is expected to experience a negative impact of approximately 500 million yen in operating profit due to revenue decline, but this impact is already factored into our financial forecast. On the other hand, we believe that the synergies created by concentrating resources on the Enterprise Growth Business, together with the stabilization and profitability improvements within the Creator Growth Business as it refocuses on priority growth areas, will bring medium- to long-term positive effects that exceed this.
Regarding the creators for whom our support has ended, the transition has already been completed, and at this point, we do not plan to make additional changes for similar reasons. From fiscal year 2026 onwards, we will proceed with business operations that balance profitability and growth, centering on the aforementioned priority areas after the reorganization.
Please explain in detail the factors driving the significant growth of the D2C/E-commerce business.
Disclosed on November 14, 2025 (Partially updated)
The D2C/E-commerce business is divided into the Creator D2C/E-commerce business and the Enterprise D2C/E-commerce business.
The Creator D2C/E-commerce business is achieving growth by concentrating resources on high-profit brands, while the number of brands handled has remained stable. Strong performance from the fitness brand "LÝFT" and merchandise brands by managed talents such as "TAKESHITA PARADISE" is driving the growth of this business segment.
In the Enterprise D2C/E-commerce business, the number of brands is increasing, mainly in Southeast Asia. When the business began in 2022, we only offered a single solution, "AnyLogi," and our main client base consisted of small-scale clients. However, we are now focusing on acquiring and deepening relationships with large-scale clients, such as global brands. We have also significantly expanded our solution offerings, moving from providing a single solution to supporting operations for high-demand solutions like live commerce and assisting with expansion into multiple countries and marketplaces. This one-stop, end-to-end support structure has become a major factor in being chosen by large-scale clients.
As a result, we achieved high growth in Southeast Asia and Japan. The natural attrition from the expiration of contracts with small-scale clients has run its course, and the number of brands has returned to a net increase. Concurrently, due to the rising proportion of large-scale clients, revenue per brand has reached a record high.
What kind of business opportunity does the launch of TikTok Shop in Japan represent for your company? Please tell us about your specific initiatives.
Disclosed on July 2, 2025 (Partially updated)
The launch of TikTok Shop in Japan represents an extremely significant business opportunity for our company, and we believe we can establish a leading position in the social commerce area in Japan.
Our company has accumulated extensive experience and expertise overseas, particularly in Southeast Asian markets. For example, we have supported major food manufacturers in expanding sales on TikTok Shop in Indonesia, and in Thailand we have been recognized as a top-tier "Prime Partner" by TikTok Shop, demonstrating our leading social commerce support track record in Asia. These achievements are supported by our specialized solution suite in this field, including our internally developed EC management tool "AnyX" and our generative AI-powered live commerce tool "AnyLive." Furthermore, in April of this year, we announced the M&A of Vibula, a prominent live commerce company in Vietnam, strengthening our organizational structure and operational know-how while accelerating global expansion.
Based on this global foundation, we are also actively advancing specific initiatives for the Japanese market. On the product side, we announced in June 2025 that our EC management tool "AnyX" and logistics management tool "AnyLogi" would begin API integration with TikTok Shop Japan. Additionally, our live commerce tool "AnyLive" has newly added Japanese language support, expanding compatible languages to 8 languages, enabling live commerce deployment across multiple languages and regions. AnyLive is also now equipped with a new function for collecting and analyzing data during live broadcasts.
Furthermore, as we recently announced, our company has been certified as an official TikTok Shop partner in Japan, in addition to our existing partnerships in Indonesia, Malaysia, the Philippines, Thailand, and Vietnam. We have established a one-stop support system for TikTok Shop that covers everything from initial planning and account management to creator collaborations, advertising, live streaming, and logistics support. By leveraging our expertise, platform, and network cultivated in Southeast Asia, we will further support the growth of brands, creators, and sellers in the Japanese market through our TikTok Shop operational support.
In terms of business development, we are already receiving numerous inquiries from clients. In anticipation of the Japanese launch of "TikTok Shop," we announced the start of providing support services for brand companies, and from May to June, we jointly held multiple seminars with TikTok for Business regarding TikTok Shop utilization. We have attracted 50 to 100 participants each time, receiving very high interest from the market and specific consultations, and we have already begun closing the deals. Our policy is to prioritize establishing market share in the Japanese market first, and steadily develop this into a medium to long-term business pillar.
Will there be no expansion into new countries or regions in the future?
Disclosed on April 2, 2025
While we are constantly considering expansion into new markets, our current focus is on prioritizing business penetration in the Asian, Indian, and Middle Eastern markets, where we believe there are sufficient opportunities and room for growth. For the time being, this is a phase of further deepening business in existing markets, and even if we do expand into Western or other emerging markets, we anticipate starting with a limited approach, such as establishing sales offices first.
On the other hand, in the medium to long term, we will carefully consider the possibility of expansion into regions outside Asia, leveraging the networks, customer base, and business models developed, while taking into account business resources.
Regarding the Chinese market, we do not currently anticipate aggressive domestic expansion in China, and the policy for China-related business is to focus on supporting outbound or inbound demand from Chinese companies.
Are there any risks you perceive for future performance or business operations?
Disclosed August 14, 2024
We operate in rapidly changing industries, so we constantly monitor changes in the industry and market. Additionally, as we expand globally, we also face geopolitical risks. However, our diversified business structure and revenue bases across various countries allow for risk distribution at the group level. Even with temporary changes in market conditions, we can expect stable growth in the Asian economy as a whole. Therefore, we believe that we have effective risk control as a group.
In business operations, more important points are recognizing the current situation regarding market changes in each country and implementing timely responses to these changes. For this, we believe that management teams in each country are crucial. While our company has diverse management members in each country, we believe that further strengthening of these country management teams is necessary to achieve higher growth in the medium to long term.
What is the revenue model for each business?
Disclosed on June 28, 2023 (Partially updated)
Our business is largely divided into the Enterprise Growth area and the Partner Growth area. In the Enterprise Growth area, we mainly provide growth support to corporate brands and the Brand Commerce area can be further sectioned into Marketing and D2C/EC businesses. The Marketing business provides offerings such as influencer marketing and digital marketing. The revenue model is one in which we receive marketing fees from corporate advertisers to implement marketing activities, and the cost of sales are payments to influencers and media (web media and mobile apps).
The D2C/EC business offers multiple solutions in the e-commerce value chain, including production, ecommerce management, and logistics. In the D2C (direct-to-consumer) business for creators, we have a product sales model, in which we hold inventory and earn revenue by selling D2C products together with creators. In the business of providing e-commerce support to corporate clients, there are multiple revenue models, including a sales-sharing model in which we receive a fixed percentage of the income generated from e-commerce sales, a model in which we provide individual solutions and receive a fixed monthly fee, and, a pay-as-you-go model in which we are compensated based on shipping fees, etc. (for AnyLogi, an inventory and logistics management solution).
In the Publisher Growth business for publishers operating web media and mobile applications, and the Creator Growth business for creators such as YouTubers and TikTokers, our primary revenue model is revenue sharing based on a fixed percentage of advertising revenue. For the revenue sharing model, we recognize advertising revenue received as gross amount and the payments to publishers and creators (other than the percentage of revenue sharing) are treated as cost of sales (whether we adopt the gross or net revenue recognition depends on the structure of contracts with publishers or creators, and the increase in gross profit margin which occurred in 2022 for the creator business was due to an increase in the proportion of contracts that are treated as net amount.). In addition, we also provide support to publishers for website/mobile app UX improvement, data analysis, and other services, and some of our offerings for a fixed fee.
Are there any other companies operating in the same business as your company?
Disclosed on June 28, 2023
Our company provides a wide range of solutions primarily in the areas of e-commerce and marketing, 1 including brand building, production management, e-commerce site development and operation, marketing, and logistics management. We have expanded our operations to 13 markets across the region, which means that there are no direct competitors in the entire business. Even when considering individual business segments, there are fewer cases of competition in the entire region of development. Usually, in each country, there are local competitors in each respective business segment separately.
Furthermore, by leveraging the benefits of scaling through global business expansion, we have invested in technologies and data utilization, provided services across Asia through cross-border operations, and offered comprehensive support along the business value chain. This distinctive positioning has led to complementary relationships with local companies in various countries, resulting in numerous cases of collaboration rather than pure competition.
Since our establishment, we have consistently invested in data and products, and we have built a strong local network and organization in each Asian market. We believe that our business foundation provides us with a competitive advantage in the respective country-specific competitive environment. We aim to continue enhancing our unique value proposition and achieve further growth in the future.
How the Company manage a multinational organization and multinational operation.
Disclosed on June 28, 2023
We have been operating in multiple countries since our establishment, and we have worked towards establishing a structure based on multinational operations. We have built a matrix organization based on two axes, country, and business. Country managers oversee operations in each country, including local teams, and are responsible for talent management, customer relations, and addressing issues specific to local markets. Regional leaders within the business axis focus on optimizing products and operations, tackling challenges that are common globally. This matrix group structure enables us to efficiently manage our business and organization.
We have also implemented a shared accounting system and CRM system throughout the company, including the companies we acquired, and have established an environment where earnings and KPI are managed in real time by business and by country, and weekly discussions are held with the head of each business in each country to review the progress and address issues faced by each business. In addition, we conduct monthly profit analysis by business unit for each country to identify businesses that require investment and businesses that need productivity improvement, and we have a system in place to respond and discuss in a timely manner.
The culture of the entire organization is very flat, and the country managers in each country work closely with other members of the group management team to improve operations in each country through mutual information sharing. In addition, for companies that have joined the group through M&A, we will promote full business integration, including organization and structure, and will establish a reporting line for each country's corporate team in both the regional and country manager's direction. We are also working to build a structure that will allow us to have more resolution and control over each country's business from the perspective of governance.
Is there any seasonality in your business?
Disclosed on April 13, 2023
On page 40 of the "Business Strategies and Growth Opportunities" document disclosed on March 29, 2023, the first quarter of the year (January-March) is expected to be a low season.
The first quarter has fewer business days and operating days than other quarters due to the New Year vacation and Lunar New Year vacations, etc. Many overseas companies (corporate customers) close their books in December and concentrate their marketing investments at the end of the fiscal year, so they often do not actively conduct marketing activities during January and Feburary. As a result, earnings, especially in our Marketing and Partner Growth businesses, tend to remain at lower levels compared to the preceding quarter. In Japan, March is the end of the fiscal year for many companies, which increases marketing spending, but January and February are also low seasons in Japan, and the Company has larger overseas businesses than Japan, resulting in the first quarter of the year being a low season.
The second (April-June) and third (July-September) quarters are not particularly seasonal, but since our business is in a growth stage, sales and gross profit are expected to be higher in the third quarter than in the second quarter.
The fourth quarter (October-December) is a high season for all businesses, as marketing activities and e-commerce sales increase for Diwali, India's biggest festival in October-November, and Christmas in December, and many overseas companies have a December fiscal year end and tend to concentrate their marketing spending at the end of the fiscal year.
The quarterly distribution of gross profit for the fiscal year ending December 2022, was 20% for the first quarter, 24% for the second quarter, 25% for the third quarter, and 31% for the fourth quarter, indicating that the contribution to earnings increases towards the latter half of the year due to both seasonality and our business growth. We expect the same seasonality and trend to continue in the fiscal year ending December 2023, and beyond.
About Financial Results and Performance
How does AI utilization help curb increases in SG&A expenses?
Disclosed on October 1, 2026
Personnel expenses account for approximately half of our SG&A, and our cost structure is such that growing workloads from business expansion tend to drive up expenses. By advancing AI utilization and the standardization of business processes, we are building a framework that enables each team member to handle more projects and tasks, with the aim of curbing the increase in SG&A relative to business growth. Through these initiatives, we are reducing the time spent on routine tasks and creating an environment in which each department can focus on higher value-added work, such as making proposals to clients and improving service quality.
Currently, headcount has remained generally flat since the beginning of FY2026, while revenue and gross profit have expanded. Although our plans for the next fiscal year onward are currently being formulated, we aim to further improve profitability by making the necessary investments in human resources based on the growth potential and workload of each business, while advancing productivity improvements through AI utilization.
Can AI utilization be expected to contribute not only to profit but also to revenue?
Disclosed on October 1, 2026
We expect our AI-powered products and services to help us acquire new clients and expand business with existing clients. We continue to develop AI-integrated products, including "AnyLive," a platform that enables multilingual, 24-hour livestreaming by AI livestreamers, as well as our proprietary AI-powered ad delivery infrastructure and automated video generation tools. These products serve as an effective entry point for winning new clients.
Furthermore, after a client first engages us for one of these AI products on a standalone basis, we expand the scope of our support to e-commerce operations, marketing support, or multi-country rollouts, thereby increasing the scale of business per client. Given our strength in delivering solutions that also cover operations in each Asian market, our policy is to further expand comprehensive rollouts across countries, platforms, and brands, using these AI products as a starting point.
Please explain the direction of headcount going forward and its impact on operating profit.
Disclosed on August 14, 2026
Headcount as of the end of Q2 was 2,330, a decrease of 22 from 2,352 at the end of Q1. This reflects improvements in productivity and appropriate control of hiring. Revenue and gross profit in Q2 tracked above our expectations, and through productivity improvements, including the use of AI, we have achieved business growth without an increase in headcount.
With respect to headcount for the remainder of FY2026, we expect increases to remain contained from Q3 onward. Our business is subject to seasonality, with performance expanding toward Q4. Given that personnel expenses account for approximately half of our SG&A, we expect the profit growth trend to continue as we grow the top line while containing the increase in personnel expenses from Q3 onward.
Some increases and decreases in the breakdown of headcount by employee category have arisen versus the previous quarter. This is because we revised the definitions of employee categories from Q2. Specifically, certain employees previously classified under "Sales and Business Development" and "Corporate" have been reclassified to "Delivery." Please note that no retroactive restatement has been made to the employee categories for Q1 and prior periods.
Could you provide an overview of the "productivity improvement through AI utilization" currently being undertaken?
Disclosed on July 1, 2026
Productivity improvement through AI utilization is a prerequisite for achieving our medium-term targets through FY2027, but its effects are conservatively estimated in our initial forecast for FY2026.
As for the overall picture of these initiatives, our internal development team is taking the lead in in-house development. Projects have been launched for each business and process and are running in parallel, and we have prioritized the automation of tasks in areas where the impact is greatest. We are taking an approach where many projects are rolled out first in specific countries, such as Japan, and then progressively expanded globally once their effectiveness is confirmed. Global rollout is already underway for multiple projects. Through these initiatives, we expect the productivity improvement effects to manifest gradually over one to two years, and we have gained a stronger conviction regarding the magnitude of the ultimate impact through our recent efforts.
Progress is moving as anticipated. As a specific example, the Marketing business in Japan has already introduced AI agents, and efficiency has advanced to the point where approximately 60% of planning operations can now be handled by AI. Currently, we are working on establishing workflows designed around AI utilization and continuous updates.
As a result of these initiatives, a framework that allows us to grow the business while curbing headcount is being realized, and our current headcount has remained generally flat from April to May. Regarding our future headcount composition, we will continue to increase front-line personnel, such as sales staff where human intervention adds high value, while curbing the hiring of delivery personnel. Therefore, although the company-wide headcount mix will change throughout 2026, we are monitoring future trends to determine whether the result will be a slight increase or a slight decrease.
What impact will the increase in AI usage have on costs?
Disclosed on July 1, 2026
We anticipate that related IT expenses will increase going forward in conjunction with the growth in AI usage and potential increases in usage fees. However, at present, these related costs account for only a minimal fraction of overall SG&A. We recognize that the positive effects generated by productivity improvements will far outweigh the increase in costs. Furthermore, we are controlling related costs, such as optimizing the models used according to the specific purpose of each project.
We anticipate that related IT expenses will increase going forward in conjunction with the growth in AI usage and potential increases in usage fees. However, at present, these related costs account for only a minimal fraction of overall SG&A. We recognize that the positive effects generated by productivity improvements will far outweigh the increase in costs. Furthermore, we are controlling related costs, such as optimizing the models used according to the specific purpose of each project.
How achievable is the FY2026 plan for the Enterprise Growth business?
Disclosed on April 3, 2026
The Enterprise Growth business consists of the Marketing business and the D2C/E-commerce business. For the current fiscal year, we project a 57% YoY increase in revenue and a 59% YoY increase in gross profit.
The Marketing business plan for the current fiscal year (revenue: up 33% YoY; gross profit: up 27% YoY) assumes a high level of growth relative to results in the second half of the previous fiscal year. We believe the slowdown in the growth rate during that period was primarily attributable to a strategic reallocation of resources to support the rapidly growing D2C/E-commerce business, rather than a deterioration in the market environment.
With this in mind, we are pursuing the following initiatives in the current fiscal year. First, we are strengthening our sales organization through the hiring and redeployment of senior sales personnel, which is expected to be substantially completed during the first half. Second, we are improving per-capita sales productivity through AI-driven workflow automation, enabling greater sales capacity. Third, we are executing cross-selling initiatives to offer social media marketing services to our existing e-commerce support clients, capitalizing on the shift in consumer behavior from social media-driven awareness to e-commerce purchases and in-store sales.
We expect these initiatives to take effect gradually and do not anticipate a rapid recovery from the first quarter. Our assumption is that improvements will progress from the second quarter onward, with the growth rate accelerating toward the second half of the year.
Meanwhile, the D2C/E-commerce business plan for the current fiscal year (revenue: up 93% YoY; gross profit: up 116% YoY) incorporates certain buffer while reflecting the current growth trajectory. As a result, the Enterprise Growth business plan is well balanced as a whole.
Please explain the business performance outlook for this fiscal year (FY2026) and the specific strategies to achieve growth.
Disclosed on February 13, 2026
For the fiscal year ending December 2026, driven by growth centered on the Enterprise Growth Business, we expect revenue of 79,110 million yen (38% increase year-over-year) and gross profit of 30,350 million yen (38% increase year-over-year). Please note that our Group's businesses exhibit seasonality weighted toward the second half of the fiscal year. Typically, the first quarter is the weakest, while performance tends to improve as we progress toward the fourth quarter.
Looking at the growth rate of gross profit, the key performance indicator for our group, by business segment, the Enterprise Growth Business is expected to increase by 59%, with a breakdown of 27% increase in the marketing business and 116% increase in the D2C/EC business. On the other hand, we anticipate a 17% decrease in the Partner Growth Business, with Publisher Growth expected to remain at the previous year's level and Creator Growth expected to decrease by 38%. By region, we expect high growth centered on Southeast Asia, as well as stable growth in Japan and other regions.
In terms of profit, while continuing personnel investment associated with business expansion, we will improve profitability by restraining personnel increases through productivity improvement and reducing the ratio of personnel costs to sales, which account for approximately half of selling, general and administrative expenses. As a result, operating profit is expected to be 3,060 million yen (70% increase year-over-year), and the operating profit margin is expected to improve from 3.1% in fiscal year 2025 to 3.9%. The breakdown of the operating profit increase is approximately 800 million yen from announced M&A deals and approximately 2.2 billion yen from organic growth of existing businesses.
We expect corporate income tax expense of 860 million yen, and profit for the period attributable to owners of the parent of 1,630 million yen (76% increase year-over-year). Note that this financial forecast assumes an exchange rate of 148 yen per US dollar on average, and incorporates a foreign exchange loss of approximately 200 million yen as foreign exchange gains/losses occurring in non-operating items.
As our business strategy, we will continue to promote the strengthening of our "enterprise growth support model utilizing e-commerce infrastructure and social data." We currently support over 1,500 companies in the Marketing business and more than 220 enterprises in the D2C/EC business, and will advance customer LTV growth and data accumulation across the customer lifecycle, from demand creation on social media to e-commerce sales expansion.
Specifically, we will first improve productivity and the value we deliver through in-house DX by leveraging generative AI and advances in our products. Second, we will expand cross-border e-commerce and integrated end-to-end social commerce support across Asia, leveraging our business foundation in 15 countries. Third, we will deepen relationships with regional enterprises operating in multiple countries and advance earnings per customer and LTV improvement by replicating successful case studies across markets.
Furthermore, as part of promoting these strategies, we will implement a strategic reorganization of the Creator Growth Business in fiscal year 2026. We will shift from a support structure centered on short-form videos to concentrate on supporting creators who can create value in social commerce, talents with high brand affinity, and live streamers with strengths in live commerce. This reorganization is expected to have a negative impact of approximately 500 million yen on operating profit in fiscal year 2026, but this is already factored into our financial forecast and is positioned as a strategic investment in anticipation of revenue expansion from 2027 onwards.
Note that there is no change to the medium-term performance targets for the fiscal year ending December 2027 announced on February 14, 2025 (revenue of 105 billion yen, gross profit of 38.5 billion yen, operating profit exceeding 6.3 billion yen, operating profit margin of 6% or more). We will advance structural improvement in profitability through accelerating growth in the Enterprise Growth Business, network reorganization, strategic M&A, and sales and operational efficiency improvements utilizing generative AI, and aim to achieve our medium-term targets.
Net income for FY2025 Q2 has decreased YoY mainly due to the impact of foreign exchange losses. Please explain the reason for these foreign exchange losses and the outlook.
Disclosed on August 14, 2025
As the Company holds foreign currency-denominated assets such as U.S. dollar deposits and accounts receivable, when exchange rates fluctuate such that Asian currencies appreciate and the U.S. dollar depreciates, foreign exchange losses are incurred as non-operating financial expenses. However, these are temporary in nature, associated with exchange rate fluctuations, and the impact on the business's fundamental earning power is considered to be limited. Therefore, beginning this quarter, the Company is disclosing adjusted net income (Note 1) for reference purposes. This figure is calculated by excluding equity compensation expenses and unrealized foreign exchange gains or losses from net income attributable to owners of the parent.
During H1 2025, the trend was an appreciation of the Japanese yen and depreciation of the U.S. dollar (The Company's month-end USD/JPY exchange rates: 156.8 at the end of December 2024, 149.8 at the end of March 2025, and 144.7 at the end of June 2025). Due to this impact, unrealized foreign exchange losses of 231 million yen (cumulative H1 total: 372 million yen) were recorded as non-operating expenses, primarily related to foreign currency-denominated assets. Consequently, the accounting-based net income attributable to owners of the parent for FY2025 Q2 was 125 million yen (cumulative H1 total: 159 million yen). On the other hand, adjusted net income (Note 1), which excludes temporary factors such as these unrealized foreign exchange losses, was 372 million yen (cumulative H1 total: 561 million yen). While foreign exchange losses may be incurred if the Japanese yen continues to appreciate, the recent trend has shifted towards depreciation of the yen. If this trend continues, foreign exchange gains will be generated instead.
(Note 1) Adjusted net income = Net income attributable to owners of the parent + Equity compensation expenses ± Unrealized foreign exchange gain/loss
Has there been any change in the business outlook for the next few years? Which business segments do you expect to be the key drivers of the growth?
Disclosed on January 8, 2025 (Revised with outdated information removed based on May 14, 2025 disclosure)
Our outlook remains unchanged from what we have communicated since our IPO in 2023. We believe we can continue to achieve high growth, supported by the significant growth potential in Asian markets. In particular, with Asian countries expected to experience medium to long-term macroeconomic growth driven by population increases, we anticipate sustained long-term growth in our overseas operations, especially in Southeast Asian markets, which are becoming increasingly important amid globalization.
We expect continued high growth particularly in our business for enterprise clients (Marketing segment and D2C/EC segment). In these segments, we support brand growth for enterprise clients across various industries, with a particular focus on clients who own consumer goods brands targeting individual consumers. For such clients, expansion into Asian markets is often a crucial initiative. We believe our unique capabilities and business scope provide significant differentiation from competitors and deliver high value to clients through: 1. our established support system across Asia and deep understanding of each market, 2. our technological capabilities to support visualization of data dispersed across countries, operational efficiency improvements, and generative AI implementation, and 3. our ability to provide comprehensive support from brand awareness to revenue generation throughout the marketing and EC processes support. Furthermore, beyond supporting Japanese companies' Asian expansion, we assist Asian companies from Korea, China, and Southeast Asia, as well as Western companies in their multi-country expansion. We anticipate that our addressable market size will continue to expand.
Additionally, in these enterprise brands support segments, there are a lot of M&A opportunities both domestically and internationally, and this business segment is easier to realize synergistic effects such as cross-selling to each segment's clients. Furthermore, as we grow both organically and through M&A and strengthen our support systems in each country, we believe we can create a virtuous cycle where our appeal to enterprise clients and our unique value proposition become increasingly stronger.
Moreover, we expect stable growth in our Partner Growth segment, which provides growth support for creators and publishers (operators of online media and mobile applications). These areas also represent growing markets globally, and we expect support opportunities to expand over the medium to long term as new creators and publishers emerge. In this context, our position is unique given our ability to provide global support and our technologically advantaged infrastructure and solutions. Furthermore, we can expect synergistic effects across our business portfolio in maximizing advertising demand, such as securing tie-up opportunities by leveraging our enterprise client network. By capitalizing on our competitive advantage of having extensive networks of enterprise clients, creators, and publishers across Asian countries, we aim to establish AnyMind as the go-to partner for business growth in Asia.
We also expect stable improvement in profitability. Over 50% of our SG&A expenses are personnel costs. Other expenses such as office rent and office-related costs are also linked to headcount, making the number of employees the primary driver of SG&A expenses. Operating across 15 countries and regions with multiple business lines, we need to maintain structures for acquiring and supporting local clients in each country, requiring workforce expansion as our business scale grows. However, we typically don't need to increase headcount at the same rate as revenue growth, so during periods of stable revenue growth, we can achieve gradual improvement in profitability.
We will continue to strengthen our position in Asian markets while pursuing both revenue growth and profitability.
Why is the marketing business continuing to grow even though the industry trends are not favorable?
Disclosed on April 1, 2024
The momentum of the overall marketing market may not be very favorable at the moment, but influencer marketing, which is an advanced marketing method, is expected to grow globally, with similar trends expected in Asia. As a reference, according to "The State of Influencer Marketing 2024" published by Influencer Marketing Hub, the global influencer marketing market size is expected to grow from $16.4 billion in 2022 to $24 billion in 2024, at an average annual growth rate of 21%.
Our marketing business is largely driven by revenue from the influencer marketing platform "AnyTag". Its strength lies in its ability to conduct campaigns utilizing a network and data of 630,000 influencers spread across Asia. We select the optimal influencers based on follower analysis data, and provide consistent support from strategy design to casting proposals and reporting. Additionally, by analyzing trends and users on social media, and measuring user reactions to posts and the effectiveness of influencer marketing initiatives, we accelerate the PDCA cycle, maximizing the effectiveness of marketing strategies.
Furthermore, we have strengthened our collaboration with major e-commerce marketplaces. Since June 2023, we have been able to conduct performance-based marketing on Lazada and Shopee, the largest e-commerce marketplaces in Southeast Asia, through collaboration. There is a high demand for influencer marketing execution support utilizing data in Asia, and we have achieved stable growth due to an increasing number of enterprises clients utilizing our services and an expansion in unit prices of projects.
When are financial results announced?
Our fiscal year ends on December 31, and we disclose our financial results on a quarterly basis. Please refer to the IR Calendar for the most recent financial announcement schedule.
What/How is the current performance?
Information on business performance can be found in Financial Highlights, and information on financial results can be found in IR Library.
What is your business outlook?
The outlook for our business performance can be found in the Summary of . Please visit our Financial Results page to view our latest financial statements.
About Stock Information
Please provide additional context on the share buyback and CEO Sogo's share acquisition announced on May 14, 2026.
Disclosed on May 14, 2026
Against the backdrop of sustained earnings growth and a sound financial foundation, the Company has today resolved to acquire treasury shares up to a total acquisition value of 500 million yen, taking into account our current share price level and the profit outlook for the current fiscal year.
The objectives of this initiative are threefold. First, to further enhance shareholder returns by conducting a share buyback in addition to dividends, which are underpinned by sustained earnings growth. Second, to improve earnings per share (EPS) and capital efficiency through the acquisition of treasury shares. Third, to secure readily deployable consideration for potential use in share exchanges in connection with M&A transactions, as well as in the design of equity-based compensation and incentive arrangements for the management teams of acquired companies.
The Company places great importance on balancing growth investments with shareholder returns. This share buyback is being conducted after ensuring that sufficient investment capacity has been secured to support continued business growth. Going forward, we will continue to pursue the enhancement of corporate value through sustained earnings growth, while further strengthening returns to our shareholders.
Separately, with respect to the acquisition of the Company's shares by Representative Director and CEO Kosuke Sogo, also announced today, this decision was made at Sogo's own initiative to demonstrate his strong commitment as the Company's top executive to medium- to long-term earnings growth. By increasing his personal shareholding, Sogo intends to further align his interests with those of shareholders and to reaffirm his resolve to drive sustainable growth and the maximization of corporate value over the medium to long term. For further details, please refer to the announcement titled "Notice Regarding Company Share Acquisition by Representative Director and CEO Kosuke Sogo", released today.
Please tell us about the intent behind shareholder return measures such as share buybacks and dividend initiation, and the balance with growth investments.
Disclosed on July 2, 2025
Our basic policy is that the investment in high growth opportunities in Asian markets will deliver the highest return on investment for our shareholders, and we prioritize growth investments as the source of sustainable enterprise value enhancement above all else. While maintaining this policy of prioritizing growth investments, we have decided to implement share buybacks and dividends with the aim of having our shares held by a broader range of investors.
Regarding dividend initiation, we made this decision with the purpose of stabilizing our shareholder base and expanding our investor demographic. The dividend level has been set within a range that does not interfere with growth investments, which are our top priority, and there is no change in our stance of pursuing high growth. Going forward, we will continue to prioritize investments to accelerate business growth above all else, while aiming for stable and continuous dividends.
The main objective of the share buyback is to secure options for enabling dynamic and flexible capital policies, such as utilizing the shares for stock swaps (stock consideration) in future M&A activities. In particular, the expansion of the share buyback framework announced on May 14 takes into account the current stock price level. We recognize that there is a possibility that the growth potential we are targeting may not be fully reflected in our current stock price, and we will maximize capital efficiency through efficient share buybacks.
Please explain the plan regarding the revision of the dividend policy and share buyback announced on May 14, 2025.
Disclosed on May 14, 2025
Regarding the share buyback plan, we have revised the content announced on February 14, 2025, to increase the maximum number of shares that can be acquired from the previous 950,000 shares, to 1,250,000 shares (approximately 2.07% of the total number of issued shares). After comprehensively considering the current share price level and capital efficiency, we have decided to expand the share buyback framework with the perspective of increasing the flexibility of our capital policy, including future growth investments such as M&A.
Additionally, we recognize that while our business continues to grow over the medium to long term, it has transitioned to a stage of stable profit generation. Considering this situation and our business performance, financial position, cash flow, and other factors comprehensively, we have decided to implement dividends for the first time. The forecast for the yearend dividend for the fiscal year ending December 2025 is 2.00 yen per share, and we aim to maintain stable and continuous dividends while continuing active growth investments in the future. At this point, we have not established a specific dividend payout ratio, but our goal is to increase dividends in accordance with profit growth.
Generally, initiating dividends tends to enhance stability as an investment target and may reduce stock price volatility, while also contributing to the expansion of the investor base that includes dividend-paying companies in their investment scope. Based on our medium to long-term revenue growth outlook, we have decided to initiate dividends with the aim of building long-term trust relationships with our shareholders, improving stock price stability, and achieving sustainable growth in corporate value.
Please highlight any notable points regarding the current shareholder composition that we should be aware of.
Disclosed on February 14, 2025
Since our founding, particularly during our pre-IPO period, we have received tremendous support from venture capital and other financial investors (hereinafter referred to as "VC investors"). Through their provision of growth capital and valuable management advice, we recognize that we have been able to establish our business foundation and achieve sustained growth. We would like to take this opportunity to express our deepest gratitude.
Generally, funds operated by venture capital firms have a redemption period of approximately 10 years, and they need to recover their investments (through the sale of acquired shares) after a certain period following their initial investment. Therefore, when there is a significant time gap between pre-IPO fundraising and the actual IPO, a situation known as "overhang" (Note 1) may occur, where share sales either take place or are expected to take place within a relatively short period after the IPO, potentially deteriorating the supply-demand balance of the shares. While stock prices fluctuate due to various factors including market conditions and business performance, a deterioration in the supply-demand balance can be one factor that suppresses stock prices.
In our case, due to our history of active fundraising since our founding, we took steps to mitigate post-IPO overhang concerns in July 2022, just before our IPO, by welcoming new shareholders who both invested in our company and purchased existing shares from shareholders (who had held their investments for a certain period). However, when we went public in March 2023, the overall stock market was weak, which resulted in a limited offering size at IPO, and the liquidity of our shares, both during the initial public offering and afterward, was not sufficient. As a result, we have received multiple concerns from investors regarding the overhang issue after our IPO.
However, looking back at the changes in our shareholder composition since our IPO, our VC investors who invested before the IPO have gradually reduced their shareholdings based on their specific circumstances, including fund redemption deadlines (please refer to Graph 1 below). As a result, as of the end of December 2024, excluding the shares invested in July 2022 just before the IPO (Pre-IPO), both the number of pre-IPO VC investors and the number of shares held by VC investors have already reached limited levels. Furthermore, to the best of our knowledge, we have not identified any major shareholders with intentions to sell shares on a scale that would significantly impact the market, and we believe that shortterm overhang concerns are now limited.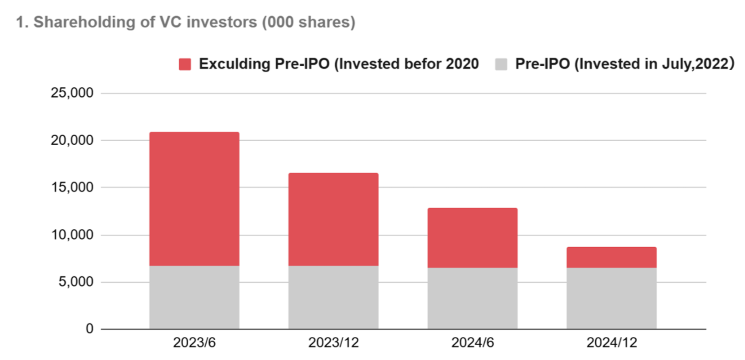 Furthermore, looking at the changes in our shareholder distribution since our IPO (please refer to Graph 2 below), the shares previously held by VC investors have been widely distributed among domestic and international institutional investors. Particularly in the six months leading up to December 2024, shareholdings increased by approximately 2.5 million shares among foreign institutional investors (Note 2) and approximately 2.1 million shares among domestic institutional investors (Note 2). We view this increase in institutional investor holdings as evidence that these investors understand and appreciate our growth potential and business model, and we would like to express our renewed gratitude for their continued support.
Moving forward, we will further strengthen our IR activities to help individual investors, as well as domestic and international institutional investors, better understand our business. We continue to be grateful for the support of all our shareholders and will devote our full efforts toward enhancing sustainable corporate value.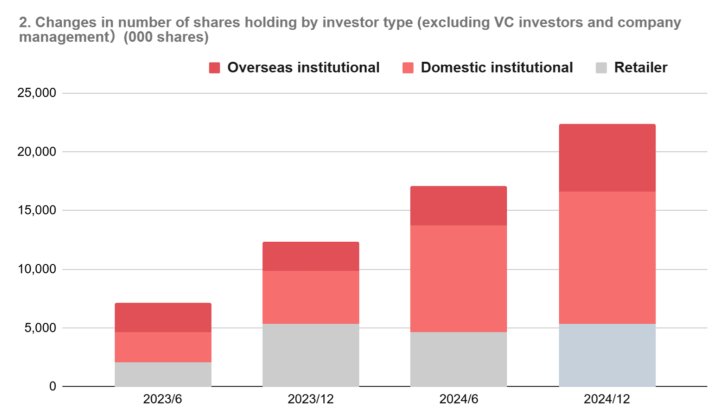 (Note 1) "Overhang" concerns refer to concerns about a potential deterioration in the supply-demand balance of shares due to anticipated large-scale share sales by major shareholders and others in the future.
(Note 2) Domestic institutional investors include general corporations, and foreign institutional investors include some individual investors.
Since our founding, particularly during our pre-IPO period, we have received tremendous support from venture capital and other financial investors (hereinafter referred to as "VC investors"). Through their provision of growth capital and valuable management advice, we recognize that we have been able to establish our business foundation and achieve sustained growth. We would like to take this opportunity to express our deepest gratitude.
Generally, funds operated by venture capital firms have a redemption period of approximately 10 years, and they need to recover their investments (through the sale of acquired shares) after a certain period following their initial investment. Therefore, when there is a significant time gap between pre-IPO fundraising and the actual IPO, a situation known as "overhang" (Note 1) may occur, where share sales either take place or are expected to take place within a relatively short period after the IPO, potentially deteriorating the supply-demand balance of the shares. While stock prices fluctuate due to various factors including market conditions and business performance, a deterioration in the supply-demand balance can be one factor that suppresses stock prices.
In our case, due to our history of active fundraising since our founding, we took steps to mitigate post-IPO overhang concerns in July 2022, just before our IPO, by welcoming new shareholders who both invested in our company and purchased existing shares from shareholders (who had held their investments for a certain period). However, when we went public in March 2023, the overall stock market was weak, which resulted in a limited offering size at IPO, and the liquidity of our shares, both during the initial public offering and afterward, was not sufficient. As a result, we have received multiple concerns from investors regarding the overhang issue after our IPO.
However, looking back at the changes in our shareholder composition since our IPO, our VC investors who invested before the IPO have gradually reduced their shareholdings based on their specific circumstances, including fund redemption deadlines (please refer to Graph 1 below). As a result, as of the end of December 2024, excluding the shares invested in July 2022 just before the IPO (Pre-IPO), both the number of pre-IPO VC investors and the number of shares held by VC investors have already reached limited levels. Furthermore, to the best of our knowledge, we have not identified any major shareholders with intentions to sell shares on a scale that would significantly impact the market, and we believe that shortterm overhang concerns are now limited.
Furthermore, looking at the changes in our shareholder distribution since our IPO (please refer to Graph 2 below), the shares previously held by VC investors have been widely distributed among domestic and international institutional investors. Particularly in the six months leading up to December 2024, shareholdings increased by approximately 2.5 million shares among foreign institutional investors (Note 2) and approximately 2.1 million shares among domestic institutional investors (Note 2). We view this increase in institutional investor holdings as evidence that these investors understand and appreciate our growth potential and business model, and we would like to express our renewed gratitude for their continued support.Moving forward, we will further strengthen our IR activities to help individual investors, as well as domestic and international institutional investors, better understand our business. We continue to be grateful for the support of all our shareholders and will devote our full efforts toward enhancing sustainable corporate value.
(Note 1) "Overhang" concerns refer to concerns about a potential deterioration in the supply-demand balance of shares due to anticipated large-scale share sales by major shareholders and others in the future.(Note 2) Domestic institutional investors include general corporations, and foreign institutional investors include some individual investors.
What are your thoughts on transitioning to the Prime Market?
Disclosed on November 14, 2024
Since our listing on the Growth Market in March 2023, thanks to shareholder support and business growth, we understand that we currently meet all formal requirements for the Prime Market except for the "profit or revenue" criterion. Regarding the "profit or revenue" requirement, there is a criterion of "total profit for the most recent two years must be 2.5 billion yen or more." If we achieve the revised consolidated earnings forecast announced on November 14th for FY2024, we would meet this requirement (based on the total profit for FY2023 and FY2024).
While we have not made any decisions regarding transitioning to the Prime Market at this time, when we meet all requirements for listing on the Prime Market (including non-formal requirements), we will consider it as one of our important management options.
Are measures to improve stock liquidity being considered?
Disclosed on April 1, 2024
After conducting the secondary offering of stock announced in September 2023, the liquidity of our company's stocks has relatively improved, and we have more shareholders holding our stocks. Therefore, we believe that the increase in the floating stock ratio due to the offering has had a certain effect, but we still have not reached the desired level of liquidity. This is not only due to the floating stock ratio but also because we need to improve the recognition of our company and awareness of our business among investors. Therefore, we do not have any plans for stock offerings at this time, and we want to focus on enhancing the recognition of our company for the time being.
In order to ensure that institutional and individual investors fully understand the potential and attractiveness of our business and the Asian market, we are committed to strengthening disclosure and maintaining ongoing communication. We believe it is crucial to build trust from the stock market by demonstrating progress in performance in line with investors' expectations, including achieving disclosed performance forecasts. Therefore, we will continue to strive in our business endeavors, solidifying our business foundation in Asia.
What is the trading unit for stocks?
The trading unit is 100 shares.
When is the annual general meeting of shareholders?
The annual general meeting of shareholders is held in late March every year.
What are the policy about dividends?
We recognize that while our business continues to grow over the medium to long term, it has transitioned to a stage of stable profit generation. Considering this situation and our business performance, financial position, cash flows, and other factors comprehensively, we announced on May 14, 2025, that we will implement a dividend for the first time. The forecast for the year-end dividend for the fiscal year ending December 2025 is 2.00 yen per share, and we anticipate the same amount for the fiscal year ending December 2026. We aim to maintain stable and continuous dividends while continuing active growth investments in the future. At this point, we have not established a specific dividend payout ratio, but our goal is to increase dividends in accordance with profit growth.
The Company's Articles of Incorporation stipulate that the Company may pay an interim dividend, while the Company's basic policy is to pay dividends from surplus twice a year: an interim dividend and a year-end dividend. In accordance with the provisions of Article 459, Paragraph 1 of the Companies Act, the Company stipulates in its Articles of Incorporation that the Board of Directors shall be the decision-making body for dividends from surplus, except as otherwise provided by laws and regulations.
The Company's Articles of Incorporation stipulate that the Company may pay an interim dividend, while the Company's basic policy is to pay dividends from surplus twice a year: an interim dividend and a year-end dividend. In accordance with the provisions of Article 459, Paragraph 1 of the Companies Act, the Company stipulates in its Articles of Incorporation that the Board of Directors shall be the decision-making body for dividends from surplus, except as otherwise provided by laws and regulations.
Who should I contact to change my address or complete other stock-related procedures?
You should contact the account management institution (securities company) where you have opened your account. Alternatively, you may contact Mitsubishi UFJ Trust and Banking Corporation, the administrator of the shareholders' register. Please refer to the Stock Memo for contact numbers and other information.
About M&A
Is there any further progress on the PMI of the three companies acquired in January?
Disclosed on May 14, 2026
PMI for all three companies is progressing well, with business synergies being generated across multiple areas. In collaboration with Bcode, we conducted a live commerce initiative on TikTok Shop in Japan for "Sunsun Sponge," a brand supported by our Enterprise E-commerce Growth business. Through a partnership with live commerce creators affiliated with Bcode, the initiative delivered over 4,300 sponge units sold across two days and a total of five hours of live streaming, with certain SKUs selling out entirely. These results demonstrate that tangible cross-selling outcomes are already emerging at an early stage.
In collaboration with MISM, within the Publisher Growth business, we have brought in-house the production of creative assets that are effective for app user acquisition. This has enabled us to offer publishers a new end-to-end solution encompassing creative production, ad delivery, performance analysis, and optimization measures. As regulations on targeted advertising continue to tighten, we are now applying data-driven optimization to the creative domain, an area where return on investment has traditionally been difficult to quantify, thereby driving improvements in advertising performance.
In collaboration with SUNSMILE, we have recently launched "AnyAI OMO (Note)," an AI Agent-powered platform that provides end-to-end support for online and offline initiatives, from effectiveness analysis to optimization and execution. This platform combines SUNSMILE's offline distribution network, backed by a proven track record of transactions with over 30,000 stores nationwide, with our expertise in data and AI utilization. Built on a foundation of AI analytics, the platform offers comprehensive support encompassing sales floor proposals, promotional design, and distribution expansion. We have already begun to see early results in a case study with "Advanced Clinicals," a U.S. skincare brand we support. By refining their sales strategy while analyzing the spillover effects of online campaigns on physical retail stores, the combined sales at the targeted stores increased by approximately 1.5 times compared to the previous month.
Going forward, we will continue to strengthen our proprietary cross-channel support framework, which comprehensively covers the spectrum from social marketing to social commerce, and drive further revenue growth through deeper collaboration across the Group.
Note: Online Merges with Offline. An initiative that integrates online and physical stores to deliver a seamless and optimal purchasing experience.
You announced the M&A of Bcode and MISM in January 2026; please explain the synergies of each business.
Disclosed on February 13, 2026
The M&A of Bcode and MISM, similar to Sun Smile, which began consolidation in January 2026, is aimed at strengthening the overall portfolio of the Enterprise Growth Business. In recent years, the behavioral shift from information contact to purchase driven by social media and video platforms has accelerated, and we are capturing this trend and positioning the establishment of competitive advantages in the social media marketing and social commerce areas as central to our strategy.
Through these M&A deals, we have established a structure capable of providing integrated end-to-end support for enterprises from demand creation to purchase conversion, and further to offline distribution.
First, MISM serves as a stable supplier of high-quality creative content through its vertical video production capabilities and stock video platform. In particular, its strength lies in providing materials with cleared usage rights and a model network to major clients where compliance is critical, thereby solidifying support for demand generation across social media channels.
Next, Bcode strengthens the purchase conversion function in the live commerce area through support for live streamers centered on TikTok LIVE. By integrating Bcode's live streamer network with our existing businesses, we can expand new sales channels originating from live streaming.
Furthermore, through the consolidation of Sun Smile, we have integrated an offline distribution network spanning over 30,000 stores in Japan. By combining our online demand creation and sales support with sales deployment in physical stores, we are establishing an integrated, end-to-end support structure for enterprises, from generating buzz on social media to in-store sales.
All of these M&A deals are aimed at responding to new consumer behavior that extends from social media awareness to purchase, and at enhancing competitiveness in marketing and commerce support. Going forward, our policy is to continue disciplined M&A on the premise of synergies with existing businesses centered on the Enterprise Growth Business.
It was mentioned that business for enterprise has been strengthened following the consolidation of SUNSMILE announced in December 2025. Could you provide more details regarding the synergies with the current business portfolio?
Disclosed on January 7, 2026
Following the consolidation of SUNSMILE, our business for enterprise has evolved into a system capable of providing integrated support from social media-driven demand generation to sales in e-commerce and offline retail. This addition of offline distribution functions, including physical stores, to our business portfolio, which was previously centered on online channels, significantly expands our scope of support.
The specific synergies consist primarily of the following two points.
First is the acquisition of a sales network that spans both online and offline channels. While we have previously provided sales support mainly in e-commerce through social media marketing and social commerce, leveraging SUNSMILE's retail distribution network, mainly in variety stores, has enabled us to provide support that links online demand generation to offline sales. Particularly in the beauty and personal care sectors, where consumer behavior from information exposure on social media to purchase is well-established, we believe that an integrated online and offline support system will be a significant competitive advantage. For details, please refer to the diagram below and the timely disclosure material titled "Regarding SUNSMILE INC. Joining AnyMind Group" published on December 18, 2025.
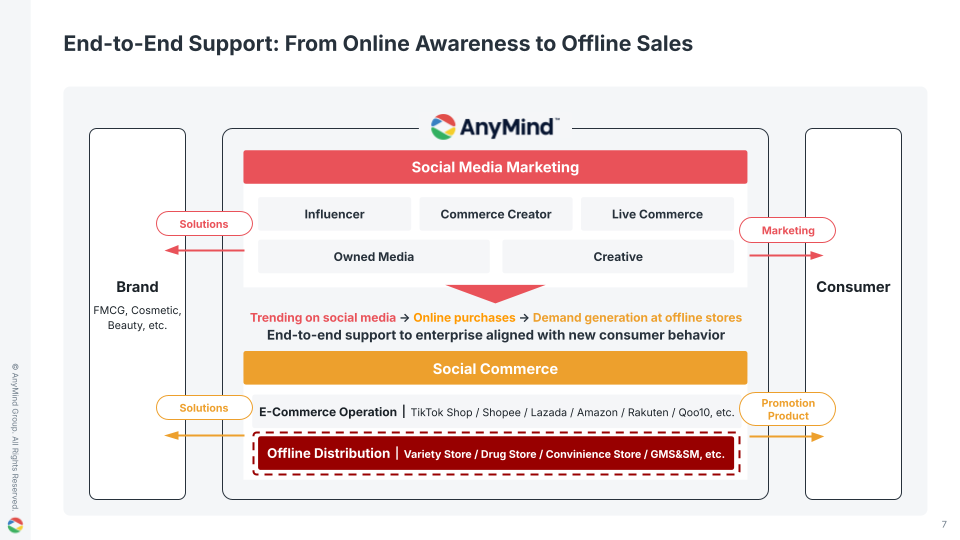
Second is the expansion of cross-selling opportunities for existing enterprise clients and brands. We can now offer our existing enterprise clients integrated support proposals that include offline distribution in addition to e-commerce. Furthermore, brands handled by SUNSMILE, such as beauty accessories and Korean cosmetics, are expected to grow by leveraging our e-commerce operations and marketing expertise. We believe this will lead to an improvement in revenue per enterprise client and per brand.
Additionally, NADESHIKO Beauty, which joined the group in October 2025, complements these efforts by handling the awareness and purchase consideration phases through its own media operations, primarily on TikTok. By combining their media operational capabilities with SUNSMILE's offline network and integrating the entire process as AnyMind Group, we will further strengthen our social media-driven support system for business for enterprise.
Based on our deep understanding of business customs and e-commerce/marketing practices across Asia, we have built a comprehensive support system that spans marketing and commerce. We believe that such a structure is not easily replicated in a short period, and we aim to establish our position as a key partner in business for enterprise within the social media marketing and social commerce fields in Asia.
Following the consolidation of SUNSMILE, our business for enterprise has evolved into a system capable of providing integrated support from social media-driven demand generation to sales in e-commerce and offline retail. This addition of offline distribution functions, including physical stores, to our business portfolio, which was previously centered on online channels, significantly expands our scope of support.
The specific synergies consist primarily of the following two points.
First is the acquisition of a sales network that spans both online and offline channels. While we have previously provided sales support mainly in e-commerce through social media marketing and social commerce, leveraging SUNSMILE's retail distribution network, mainly in variety stores, has enabled us to provide support that links online demand generation to offline sales. Particularly in the beauty and personal care sectors, where consumer behavior from information exposure on social media to purchase is well-established, we believe that an integrated online and offline support system will be a significant competitive advantage. For details, please refer to the diagram below and the timely disclosure material titled "Regarding SUNSMILE INC. Joining AnyMind Group" published on December 18, 2025.
Second is the expansion of cross-selling opportunities for existing enterprise clients and brands. We can now offer our existing enterprise clients integrated support proposals that include offline distribution in addition to e-commerce. Furthermore, brands handled by SUNSMILE, such as beauty accessories and Korean cosmetics, are expected to grow by leveraging our e-commerce operations and marketing expertise. We believe this will lead to an improvement in revenue per enterprise client and per brand.
Additionally, NADESHIKO Beauty, which joined the group in October 2025, complements these efforts by handling the awareness and purchase consideration phases through its own media operations, primarily on TikTok. By combining their media operational capabilities with SUNSMILE's offline network and integrating the entire process as AnyMind Group, we will further strengthen our social media-driven support system for business for enterprise.
Based on our deep understanding of business customs and e-commerce/marketing practices across Asia, we have built a comprehensive support system that spans marketing and commerce. We believe that such a structure is not easily replicated in a short period, and we aim to establish our position as a key partner in business for enterprise within the social media marketing and social commerce fields in Asia.
The acquisition of shares in SUNSMILE is large-scale compared to past projects, and the funds for this project will be allocated from borrowings. Given the premise of continuing M&A in the future, are you considering financing methods other than financial institutions, such as a public offering?
Disclosed on January 7, 2026
At this time, we are not considering any specific plans for equity financing, such as public offerings, as our basic policy is to raise funds by utilizing our borrowing capacity.
Borrowings for this share acquisition will amount to approximately 4.1 billion yen. However, as of the end of September 2025, we held approximately 3.1 billion yen in net cash, and we recognize that financial leverage remains at an appropriate level even after the acquisition. We will continue to maintain a capital policy that emphasizes a balance between financial soundness and growth investment.
Furthermore, we believe there is sufficient backing in terms of profitability. The Company's consolidated operating profit forecast for the fiscal year ending 2025 is 1.7 billion yen. In addition, SUNSMILE, which will be consolidated starting January 2026, recorded an actual operating profit of 670 million yen (IFRS basis) for the most recent 12 months as of the end of June 30, 2025, provided here as a reference value. By consolidating a business with a solid earnings base, we expect profit levels to steadily increase.
Based on these factors, we believe that even after the current borrowing, we have secured a sufficient financial foundation and borrowing capacity for future growth investments. Regarding future financing, our policy is to consider the optimal means while taking share dilution and the impact on existing shareholder value into full consideration.
What is your company's policy, if any, when considering M&A, and what is your policy for reducing risks related to M&A?
Disclosed on May 12, 2023
The following are points of focus when conducting M&As:
1. Resolution/deep understanding for the target business
Our basic policy is to consider M&A in a manner that complements existing businesses and business domains. Therefore, when considering M&A, we believe that having a high resolution of the business environment, business model, and risks and opportunities of the target business will form the basis for various discussions, including management synergies and business integration.
2. Direction and culture fit with the target company's management members
In principle, our M&A activities are based on the premise of business integration, and the objective is often to acquire organizations, networks, etc., through M&A. One of these is the acquisition of talented management members, and we aim to strengthen our own management structure by having people with extensive management experience join us through M&A. In the process of conducting M&A, we hold discussions with the target company's management team to gain a mutual understanding of not only the business of both companies, but also the direction and values that the management team is aiming for as individuals. We also believe that having the target company's management team makes the integration process effective in accelerating the process.
3. Possibility of multiple synergies across different time periods
When conducting M&A activities, it is important that we assume synergies between the two companies. In many cases, we can expect immediate synergies based on our network, organization and technology (e.g., cross-border initiatives, etc.), since we are constantly expanding into multiple business areas and businesses. We also believe that it is desirable to be able to envision as many synergistic scenarios as possible, and to strike a balance between synergies that can be realized immediately and synergies that are expected to occur over the longer term.
In addition, we take the following measures to reduce the risks involved in the M&A process, which has inherent elements of uncertainty.
1. Proactive business integration after M&A
In principle, we aim to quickly unify the governance structure and granularity of business management, by proactively integrating organizations, businesses and systems after M&A, and integrate them into our business management system and structure. We view this as an important step to ensure stable growth of the Group over the medium to long term by creating synergies, identifying business risks and opportunities, and aligning corporate culture through business integration.
2. Implement a multifaceted due diligence process prior to M&A
When implementing M&A, our internal policy is to appoint local advisors for financial, tax, and legal due diligence, as well as valuation evaluation of the target company, and conduct analysis based on the risks and constraints unique to each country. In addition, as part of the process of deepening our understanding of the business, our team and management team will conduct due diligence on the business to assess the probability of the business plan and growth potential and risks of the business model. Through this multifaceted evaluation process, we understand the risk associated with the target business and verify the possibility of business integration.